Stock Deep Dive · 2026-08-04
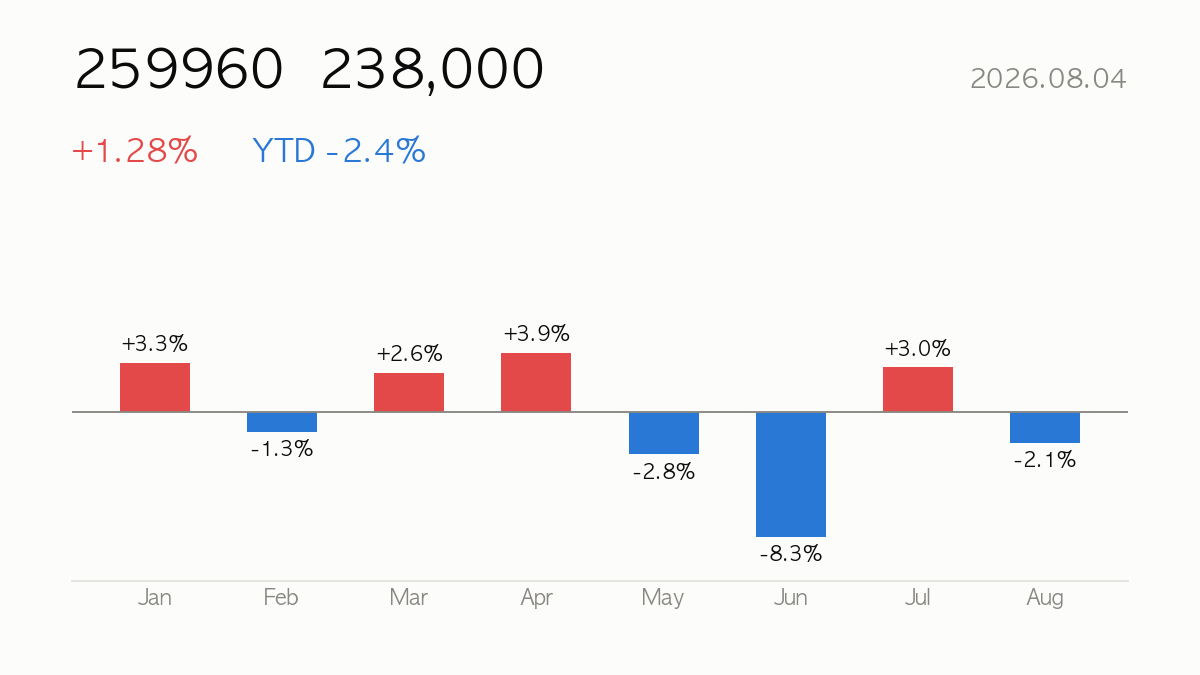
Krafton (259960) closed at ₩238,000, up 1.28% on the day. Year-to-date return is -2.4%, sitting at 27% of its 52-week range. Earnings for the quarter were reported on 2026-07-29. Listed in Seoul — for USD-based investors, KRW moves add an FX layer on top of the stock’s local return.
|
Close
₩238,000
+1.28% · YTD -2.4%
|
Market Cap
₩10.73T
Electronic Gaming & Multimedia
|
Forward P/E
9.6x
PER 12.2x
|
52-wk Range
27%
High ₩344,000 · Low ₩199,300
|
🔍 At a Glance
Krafton’s fundamentals look robust on paper: quarterly revenue jumped 94.9% YoY, operating margin sits at a healthy 30.3%, and the forward PER of 9.6 (trailing 12.2) looks inexpensive against a consensus “buy” from 23 analysts with an average target of ₩358,335 — roughly 50% above the current ₩238,000 price. The bear case is equally visible: shares are down 16% over three months, trade below both the 60- and 200-day moving averages, sit in just the 27th percentile of their 52-week range, and face persistent questions about growth durability once the PUBG franchise matures.
🏢 How It Makes Money
Krafton, listed on the KOSPI and classified under Communication Services, is best known as the studio behind PUBG (PC, mobile, and console versions), supplemented by other game titles, mobile app distribution, consulting/investment activities, and video content production. Its business model concentrates heavily on a single hit franchise, making the pace of new releases and diversification a key swing factor for revenue.
📈 Quarterly Results — Is Business Growing?
| Quarter | Revenue | Op. Income | Net Income | Op. Margin |
|---|---|---|---|---|
| 25Q1 | ₩874.2B | ₩457.3B | ₩372.0B | 52.3% |
| 25Q2 | ₩662.0B | ₩246.1B | ₩15.2B | 37.2% |
| 25Q3 | ₩870.6B | ₩348.6B | ₩367.5B | 40.0% |
| 25Q4 | ₩919.7B | ₩2.5B | ₩-20.0B | 0.3% |
| 26Q1 | ₩1.37T | ₩561.6B | ₩514.8B | 40.9% |
| 26Q2* | ₩1.29T | ₩410.9B | ₩-27.4B | 31.8% |
* 26Q2 figures come from the company’s preliminary earnings disclosure filed with Korea’s DART on 2026-07-29. They are unaudited and will be replaced once the reviewed quarterly or half-year report is filed.
Latest-quarter revenue up +94.9% versus the same quarter a year ago.

💡 Korea Market 101
⚖️ Valuation — Cheap or Expensive?
| Metric | Value | How to read it |
|---|---|---|
| P/E (trailing) | 12.2x | Price vs last 12 months’ earnings |
| P/E (forward) | 9.6x | Price vs next 12 months’ expected earnings — growth hopes baked in |
| P/S | 2.8x | Price vs revenue — for high-growth names with thin profits |
| P/B | 1.5x | Price vs book value — below 1x means priced under liquidation value |
| EV/EBITDA | 5.8x | Enterprise value (incl. debt) vs cash generation |
Peer comparison
| Name | Mkt Cap | P/E | Fwd P/E | P/S |
|---|---|---|---|---|
| KRAFTON | ₩10.73T | — | 9.6x | 2.8x |
| NC | ₩4.68T | — | 10.6x | 2.7x |
| Netmarble | ₩3.22T | — | 10.0x | 1.1x |
💡 Korea Market 101
🎯 Street Consensus
- Price target (mean): ₩358,335
- Target high / low: ₩410,000 / ₩297,000
- Implied upside: +50.6%
- Rating: Buy (1.6/5)
- Analysts covering: 23
- Last earnings: 2026-07-29 — reported
💡 Korea Market 101
📉 Price Action — Technical Check

| Indicator | Value | How to read it |
|---|---|---|
| RSI (14d) | 53.7 | Above 70 overbought · below 30 oversold |
| vs 60-day MA | -3.2% | Above/below the medium-term trend |
| vs 200-day MA | -4.8% | Above/below the long-term trend |
| Golden/death cross | 50-day below 200-day (bearish alignment) | 50-day MA crossing above (golden) or below (death) the 200-day |
| Volume (vs 20d avg) | 1.1x | 2x+ means a spike in market attention |
💡 Korea Market 101
📰 Recent News
- 259960 Stock Price and Chart — KRX:259960 — TradingView
- KRAFTON, Inc. announces an Equity Buyback for 409,836 shares. — marketscreener.com
- Can The KRAFTON CEO Keep His Promise? Strong Earnings, Weak Stock, and a Looming Reappointment Decision — Inven Global
- When Should You Buy KRAFTON, Inc. (KRX:259960)? — simplywall.st
- Concerns over post-PUBG growth prompts NPS to unload Krafton shares — The Korea Times
- Krafton Reappoints CEO Kim Chang-han Through March 2029 — thelec.net
How to read these headlines
The common thread is a tension between confidence and caution: management’s reappointment of CEO Kim Chang-han through 2029 and a fresh buyback signal long-term conviction, while the National Pension Service trimming its stake reflects institutional skepticism about growth beyond PUBG. This divergence may weigh on sentiment even as valuation multiples look reasonable, making the CEO’s ability to demonstrate a credible post-PUBG growth story worth confirming at the next earnings update.
Headlines are credited to their publishers — click a headline to open the original article. The commentary is written by this site and does not represent the views of any publisher.
💡 Korea Market 101
🔭 Scenarios & What to Watch
The next earnings release on November 3, 2026 will be the key checkpoint for whether the 94.9% revenue growth pace can be sustained or was a one-off comparison effect. Watch for pipeline updates on new titles beyond PUBG, execution of the announced share buyback, and whether the stock can reclaim its 60- and 200-day averages (currently -3.2%/-4.8% below). USD-based investors should also track KRW/USD moves, which affect returns independent of share performance. RSI at 53.7 suggests no extreme technical positioning either way.
💡 Korea Market 101
📚 All stock analysis · More on Krafton · Market report for this session
Stock report · published 2026-08-04 16:00 KST
For information only — a summary of public data, not a recommendation to buy or sell any security. Source data (Yahoo Finance and others) may be delayed or contain errors. All investment decisions are your own responsibility.
Leave a Reply