Stock Deep Dive · 2026-08-10
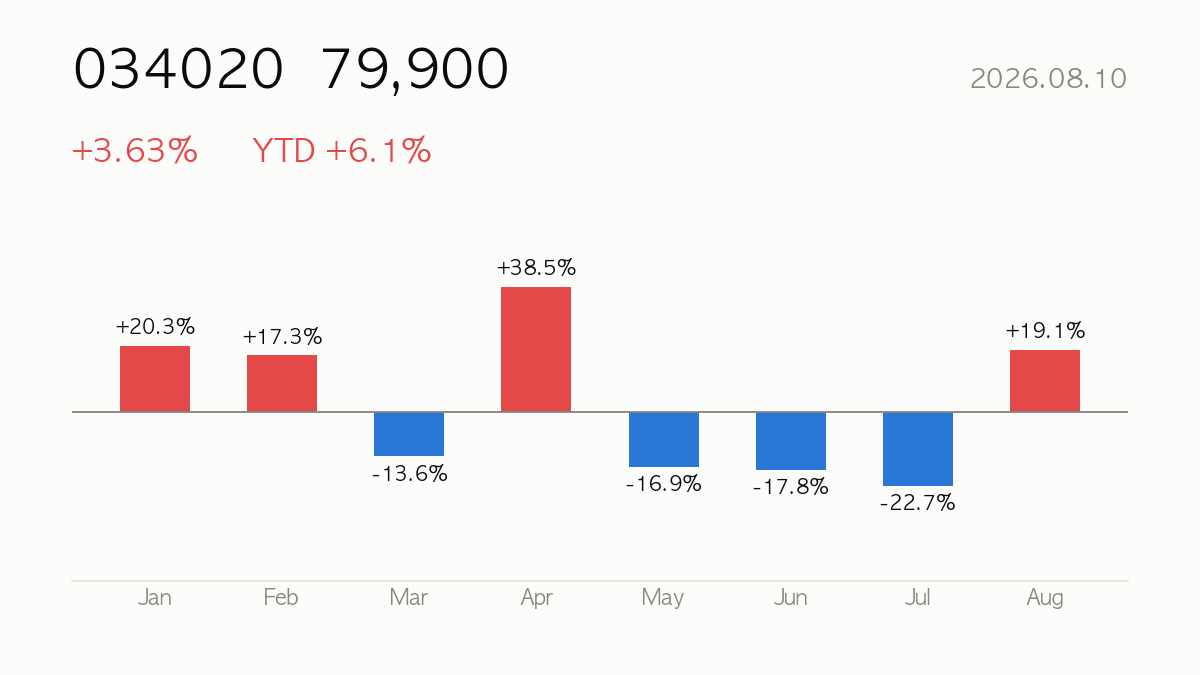
Doosan Enerbility (034020) closed at ₩79,900, up 3.63% on the day. Year-to-date return is +6.1%, sitting at 33% of its 52-week range. Listed in Seoul — for USD-based investors, KRW moves add an FX layer on top of the stock’s local return.
|
Close
₩79,900
+3.63% · YTD +6.1%
|
Market Cap
₩51.07T
Specialty Industrial Machinery
|
Forward P/E
76.9x
PER 330.8x
|
52-wk Range
33%
High ₩139,200 · Low ₩51,100
|
🔍 At a Glance
Doosan Enerbility is riding a wave of retail enthusiasm and SMR/gas-turbine order momentum, with 1-month gains of +9.2% and Q1 orders reportedly up 62% on data-center-driven demand. Yet valuation looks stretched — PER of 330.8x and EV/EBITDA of 41.9x sit uneasily against a 4.9% operating margin and 2.4% ROE, and the stock remains down 37.1% over three months and 12.5% below its 200-day average.
🏢 How It Makes Money
The company manufactures power generation equipment — boilers, turbines, generators — and is expanding into new-energy solutions including small modular reactors, wind, hydrogen, and energy storage, alongside gas turbines and EPC work for thermal plants. It also runs a diversified construction and casting/forging business serving power, marine, and industrial clients globally, with TTM revenue of ₩17.57T growing 3.0% YoY.
📈 Quarterly Results — Is Business Growing?
| Quarter | Revenue | Op. Income | Net Income | Op. Margin |
|---|---|---|---|---|
| 25Q1 | ₩3.75T | ₩142.5B | ₩-68.9B | 3.8% |
| 25Q2 | ₩4.57T | ₩271.1B | ₩130.9B | 5.9% |
| 25Q3 | ₩3.88T | ₩137.1B | ₩-50.1B | 3.5% |
| 25Q4 | ₩4.86T | ₩212.1B | ₩72.8B | 4.4% |
| 26Q1 | ₩4.26T | ₩233.5B | ₩0.8B | 5.5% |
| 26Q2* | ₩4.72T | ₩314.3B | ₩157.6B | 6.7% |
* 26Q2 figures come from the company’s preliminary earnings disclosure filed with Korea’s DART on 2026-07-27. They are unaudited and will be replaced once the reviewed quarterly or half-year report is filed.
Latest-quarter revenue up +3.0% versus the same quarter a year ago.

💡 Korea Market 101
⚖️ Valuation — Cheap or Expensive?
| Metric | Value | How to read it |
|---|---|---|
| P/E (trailing) | 330.8x | Price vs last 12 months’ earnings |
| P/E (forward) | 76.9x | Price vs next 12 months’ expected earnings — growth hopes baked in |
| P/S | 2.9x | Price vs revenue — for high-growth names with thin profits |
| P/B | 6.6x | Price vs book value — below 1x means priced under liquidation value |
| EV/EBITDA | 41.9x | Enterprise value (incl. debt) vs cash generation |
Peer comparison
| Name | Mkt Cap | P/E | Fwd P/E | P/S |
|---|---|---|---|---|
| Doosan Enerbility | ₩51.07T | — | 76.9x | 2.9x |
| HD HYUNDAI HEAVY INDUSTRIES | ₩55.82T | — | 14.9x | 2.8x |
| Hanwha Ocean | ₩28.92T | — | 14.7x | 2.3x |
| GE Vernova Inc. | $263.76B | 28.4x | 39.8x | 6.4x |
💡 Korea Market 101
🎯 Street Consensus
- Price target (mean): ₩128,529
- Target high / low: ₩177,000 / ₩100,000
- Implied upside: +60.9%
- Rating: Strong Buy (1.4/5)
- Analysts covering: 20
💡 Korea Market 101
📉 Price Action — Technical Check

| Indicator | Value | How to read it |
|---|---|---|
| RSI (14d) | 66.3 | Above 70 overbought · below 30 oversold |
| vs 60-day MA | -8.4% | Above/below the medium-term trend |
| vs 200-day MA | -12.5% | Above/below the long-term trend |
| Golden/death cross | 50-day below 200-day (bearish alignment) | 50-day MA crossing above (golden) or below (death) the 200-day |
| Volume (vs 20d avg) | 0.8x | 2x+ means a spike in market attention |
💡 Korea Market 101
📰 Recent News
- SK Hynix, Doosan Enerbility Surpass 1 Million Shareholders — 조선일보
- Samsung Securities Offers Shares of Samsung Electronics, Hyundai Motor, and Doosan Enerbility to New Customers — 아시아경제
- Doosan Enerbility Wins Rolls-Royce SMR Work: Q1 Orders Jump 62% Amid Data Center Push — techtimes.com
- Doosan Enerbility stock surge drives earnings shock as RSU costs hit profits – CHOSUNBIZ — Chosunbiz
- PECC2 signs AiP for Cong Thanh LNG project — LNG Industry
- 034020 Stock Price and Chart — KRX:034020 — TradingView
How to read these headlines
The common thread is retail-driven momentum: crossing one million shareholders and being pushed to new brokerage customers reflect strong domestic demand, fueled by genuine strategic wins like the Rolls-Royce SMR deal and data-center-linked order growth. But that same share-price surge carries a direct earnings mechanism — it inflated RSU (stock-based compensation) costs enough to trigger an “earnings shock,” meaning investor enthusiasm and reported profitability can move in opposite directions, worth confirming in upcoming results.
Headlines are credited to their publishers — click a headline to open the original article. The commentary is written by this site and does not represent the views of any publisher.
💡 Korea Market 101
🔭 Scenarios & What to Watch
Bulls point to the Rolls-Royce SMR partnership and a reported 62% jump in Q1 orders as evidence that data-center power demand is translating into real backlog growth; a sustained pipeline could eventually lift the thin 4.9% margin. Bears note that a PBR of 6.6x and forward PER of 76.9x already price in much of that optimism, leaving little room for disappointment despite 20 analysts holding a strong_buy view with an average target of 128,528.70. Watch the next quarterly earnings release for order-to-revenue conversion and any further RSU-related compensation drag on profits, plus whether shares can reclaim their 60-day (-8.4%) and 200-day (-12.5%) moving averages.
💡 Korea Market 101
📚 All stock analysis · More on Doosan Enerbility · Market report for this session
Stock report · published 2026-08-10 16:00 KST
For information only — a summary of public data, not a recommendation to buy or sell any security. Source data (Yahoo Finance and others) may be delayed or contain errors. All investment decisions are your own responsibility.
Leave a Reply